By: Sid Peddinti, Esq.
Dear Athlete,
I’m sure you’ve read the headlines – bankruptcies, probate battles, and high-stakes divorces that wipe athletes clean. In the high-stakes world of professional sports, the transition from a multi-million dollar contract to financial insolvency is a path traveled by far too many.
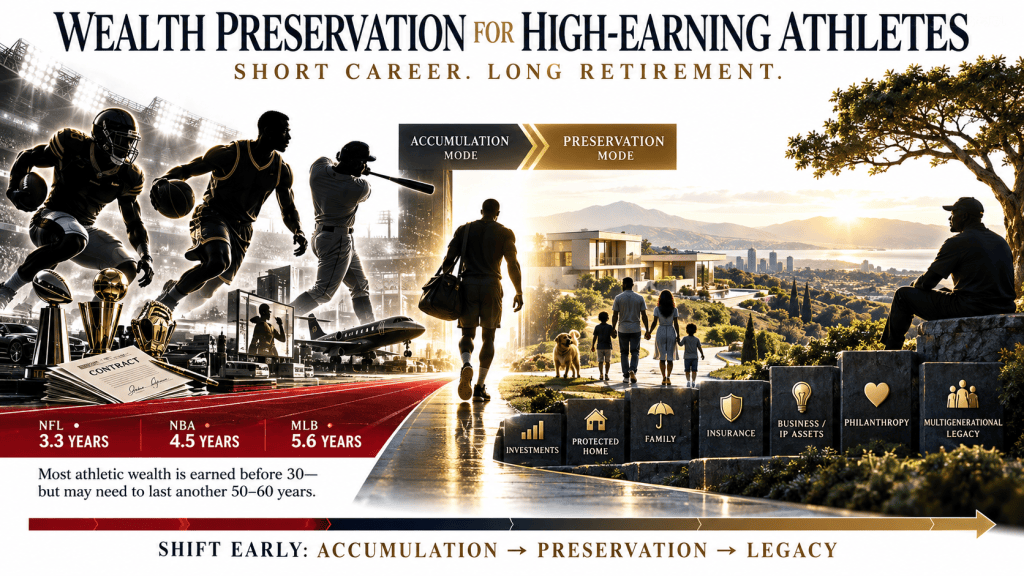
While the headlines often focus on the “bling” and the “bust,” the underlying cause is rarely just “spending too much.” It is a systemic failure to transition from a “temporary earner” to a “permanent institution“.
To survive the modern landscape of predatory lending, high taxation, and market volatility, athletes must adopt a “Double Bottom Line” mentality.
This involves a sophisticated dual-entity structure: a Private Foundation for goodwill, trust, and tax redirection, and a For-Profit Holding Company for intellectual property, investments, and asset protection.
Let’s explore this together.
⚡ Key Takeaways
- The Cautionary Tales: Latrell Sprewell, Derrick Coleman, and Eddy Curry serve as critical case studies on how predatory loans and illiquid real estate can dismantle a $100M fortune.
- The Institutional Shift: Athletes must stop viewing themselves as employees and start operating as “Family Offices.”
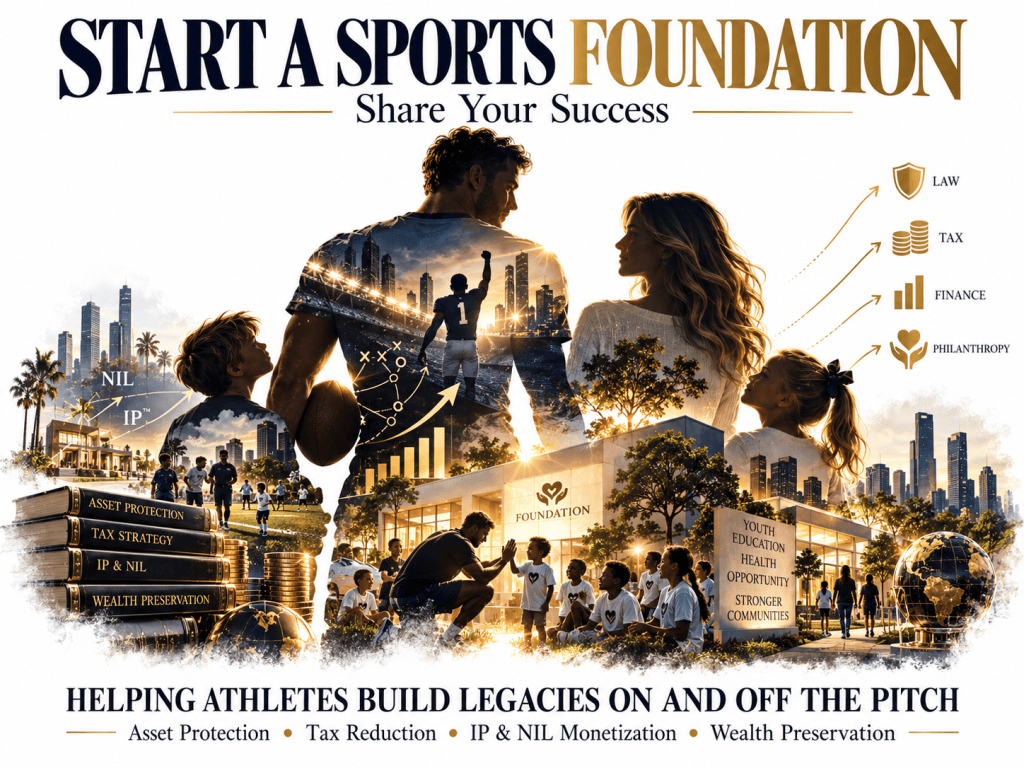
- The 501(c)(3) Strategy: A foundation is not just for charity; it is a networking powerhouse that builds “Philanthropic Tax Redirection” and long-term career connections.
- The Holding Company Model: Managing NIL (Name, Image, Likeness) and IP through a for-profit entity allows for strategic expense offsetting and asset shielding.
- NIL Financial Literacy: Early-career intervention is the only way to combat the “pro-athlete-to-broke” pipeline.
- Athlete To Owner: Transitioning from working for a sport team to building, funding, and running one.
Table of Contents
- The Anatomy of Financial Collapse: Three Case Studies
- Latrell Sprewell: The Seizure of the “Compassionate”
- Derrick Coleman: The Detroit Real Estate Trap
- Eddy Curry: The 85% Interest Predatory Spiral
- The Double Bottom Line: Foundation & Holding Company
- The Private Foundation (501(c)(3)): Building the Legacy
- Tax Redirection and Goodwill
- Networking and Institutional Connections
- The For-Profit Holding Company: Protecting the Brand
- NIL and IP Management
- Strategic Expense Offsetting
- Synergy: How the Two Entities Work Together
- Comparison: Foundation vs. Holding Company
- Frequently Asked Questions (FAQ)
- Call To Action & Next Steps
- References & Sources
The Anatomy of Financial Collapse: Three Case Studies
The history of the NBA is littered with financial cautionary tales. These are not just stories of bad luck; they are examples of how a lack of structural protection can leave even the highest earners vulnerable to total loss.
Latrell Sprewell: The Seizure of the “Compassionate”
Latrell Sprewell earned approximately $97 million during his 13-season NBA career. Despite this massive accumulation of wealth, his financial downfall was swift and public.
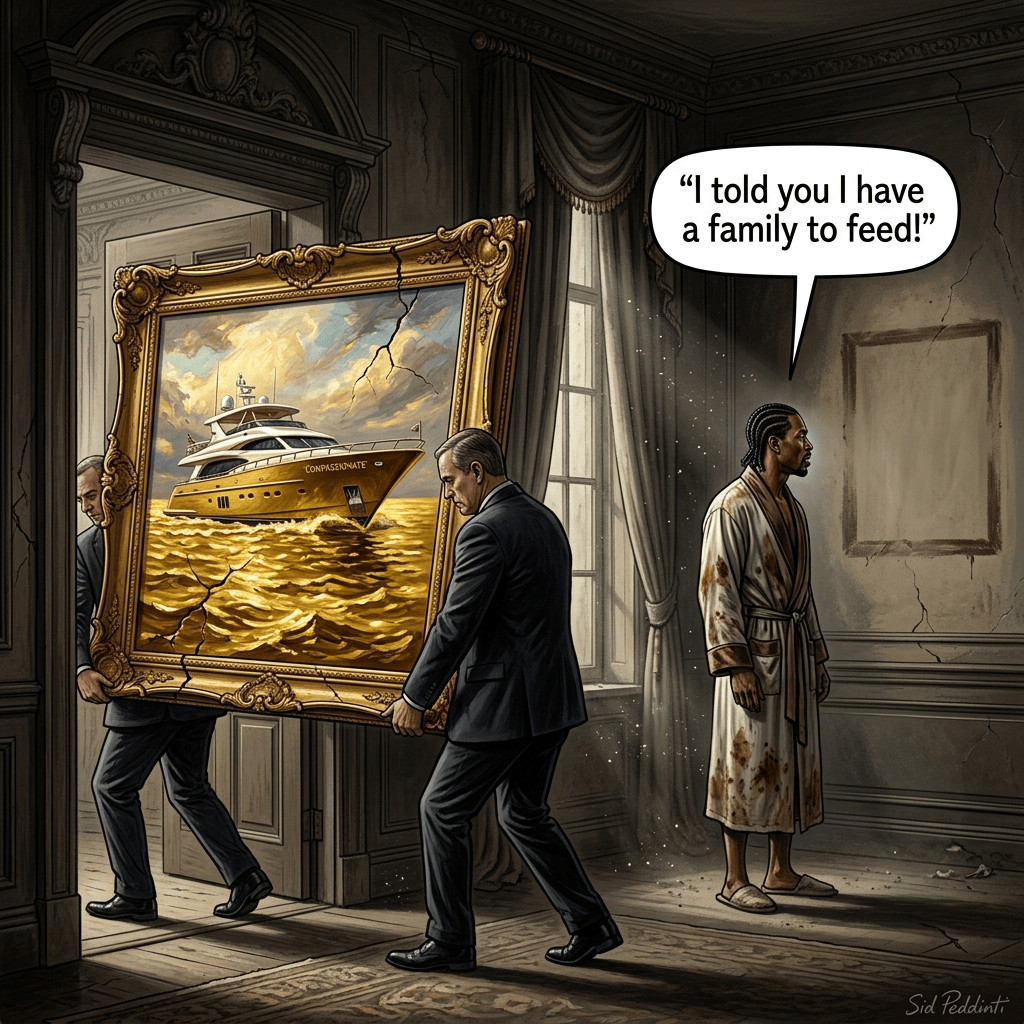
In 2007, federal marshals seized his 70-foot luxury yacht, ironically named “Compassionate,” after Sprewell defaulted on a $1.5 million loan. The vessel, once a symbol of his success, was sold at auction for a fraction of its value. This was only the beginning. By 2008, Sprewell faced foreclosure on multiple primary residences, including a home in Milwaukee and a mansion in Westchester County, New York. The collapse was driven by a combination of unpaid taxes, bank defaults, and a lack of liquid assets to cover high-maintenance luxury liabilities.
Derrick Coleman: The Detroit Real Estate Trap
Derrick Coleman, the #1 overall pick in the 1990 NBA Draft, earned an estimated $87 million on the court. Unlike many who “blew it” on parties, Coleman’s downfall was rooted in an attempt to do good. He invested heavily in his hometown of Detroit through Coleman Group LLC, aiming to revitalize the city with real estate projects and local businesses.
However, the 2008 financial crisis and the subsequent collapse of the Detroit property market proved fatal. In 2010, Coleman filed for Chapter 7 bankruptcy, reporting $18.5 million in liabilities against only $1 million in assets. He owed money to nearly 100 different creditors, ranging from major banks to local contractors. His case highlights the danger of “illiquid concentration”—putting too much capital into high-risk real estate without a protective holding structure.
Eddy Curry: The 85% Interest Predatory Spiral
Eddy Curry’s story is perhaps the most harrowing example of predatory lending in professional sports. Despite earning over $70 million, Curry found himself in a financial death spiral.
In a moment of liquidity need, Curry took out a personal loan from All-Star Capital that carried a staggering 85% interest rate. This predatory debt ballooned rapidly. When he could no longer keep up with the payments, the situation escalated to court-ordered vehicle seizures and the garnishment of his bank accounts to satisfy a $1.2 million judgment. At the height of his crisis, Curry’s monthly expenses were reported to be over $570,000, including supporting a large extended family and paying off high-interest debt.
The Double Bottom Line: Foundation & Holding Company
To avoid the fates of Sprewell, Coleman, and Curry, modern athletes must adopt a “Double Bottom Line” strategy. This means measuring success not just by net worth, but by institutional impact and asset protection.
The goal is to move away from being a “person with a bank account” to being a “conglomerate with a mission.” This is achieved by running two distinct entities side-by-side: a 501(c)(3) Private Foundation and a For-Profit Investment Holding Company.
The Private Foundation (501(c)(3)): Building the Legacy
Starting a sports foundation the moment you sign your first contract is one of the most strategic moves an athlete can make. It is not merely about “giving back”; it is about Philanthropic Tax Redirection.
Tax Redirection and Goodwill
Instead of sending 37% or more of your top-line earnings to the IRS, a portion of that money can be redirected into your own foundation. These contributions are tax-deductible, lowering your overall taxable income.
- The Benefit: You maintain “control” over where that money goes. Instead of it disappearing into the federal budget, it stays in an entity you control, building your name and your community.
Networking and Institutional Connections
A foundation allows an athlete to donate to sports programs, university clubs, and even stadium projects. This does more than just put a name on a wall; it builds high-level connections.
- The Strategy: By funding a university program, you gain access to the Board of Trustees, wealthy boosters, and corporate sponsors. These are the people who will provide your next business deal, your next investment opportunity, or your post-retirement executive role.
- Grants and AI Experiments: Foundations can apply for government and private grants. Imagine your foundation hosting AI-driven athletic experiments or sports education programs. You can work for your foundation, take a reasonable salary, and even involve your family members in the operations, creating a multi-generational career path.
The For-Profit Holding Company: Protecting the Brand
While the foundation handles the “goodwill,” the For-Profit Holding Company handles the “business.” This entity should be the owner of your most valuable asset: your Intellectual Property (IP).
NIL and IP Management
In the era of NIL (Name, Image, and Likeness), an athlete’s brand is a commercial enterprise. By placing your NIL and IP rights inside a holding company, you separate your personal identity from your business activities.
- Asset Protection: If the holding company faces a lawsuit or a failed business venture, your personal assets (and your foundation’s assets) remain shielded.
Strategic Expense Offsetting
A holding company allows you to manage expenses more strategically. Training, travel, marketing, and professional services can be billed through the company, offsetting the income generated from endorsements and investments. This is a core component of Athlete Family Offices, where the athlete’s life is managed with the same rigor as a Fortune 500 company.
Synergy: How the Two Entities Work Together
The magic happens when the Foundation and the Holding Company work in tandem.
- Contracting: Your foundation can contract with your holding company for specialized services (like marketing the foundation’s events), keeping the capital within your ecosystem.
- Legacy Building: The foundation builds the reputation and the “seat at the table,” while the holding company executes the private equity and real estate deals that arise from those connections.
- Family Involvement: You can encourage your children and family to work within these structures, teaching them NIL Financial Literacy and business management from a young age.
Comparison: Foundation vs. Holding Company
| Feature | Private Foundation (501(c)(3)) | For-Profit Holding Company |
|---|---|---|
| Primary Purpose | Philanthropy, Goodwill, Networking | Wealth Accumulation, IP Management |
| Tax Status | Tax-Exempt (Contributions Deductible) | Taxable (Strategic Offsets) |
| Ownership | Controlled by Board/Founder | Owned by Athlete/Family |
| Revenue Sources | Donations, Grants, Endowments | NIL Deals, Investments, Licensing |
| Key Benefit | Tax Redirection & Reputation | Asset Protection & Privacy |
| Family Role | Can draw a reasonable salary | Can be shareholders/employees |
Frequently Asked Questions (FAQ)
Why did Latrell Sprewell lose his yacht?
Sprewell defaulted on a $1.5 million loan used to purchase the yacht. Because the asset was likely held in his personal name or a poorly structured entity, federal marshals were able to seize it directly when payments stopped.
What is “Philanthropic Tax Redirection”?
It is the practice of donating a portion of high-earning income to a self-controlled 501(c)(3) foundation. This reduces the athlete’s taxable income while keeping the funds within an entity they manage for charitable purposes.
How does a holding company protect an athlete from predatory loans?
A holding company provides a layer of separation. By requiring all loans and business deals to go through a corporate entity with professional oversight, it becomes much harder for predatory lenders to target an athlete’s personal bank accounts or primary residences.
Can an athlete really take a salary from their own foundation?
Yes, as long as the salary is “reasonable” and for actual services rendered (such as Executive Director or Program Coordinator). This is a common way for athletes to maintain a steady income stream after their playing days are over.
Call To Action & Next Steps
The transition from “Player” to “Institution” requires a shift in mindset and a sophisticated legal structure. Don’t wait until your career is halfway over to protect what you’ve earned.
Ready to build your legacy?
Learn how to structure your Athlete Family Office and Foundation today. Take a second to fill out a complimentary assessment to explore how you can protect your assets, reduce and redirect taxes, and build a legacy at the same time.
References & Sources
- U.S. Bankruptcy Court Records: In re Derrick Coleman, Eastern District of Michigan (2010).
- Federal Marshal Records: Seizure of the vessel “Compassionate” (2007).
- Internal Revenue Service (IRS): Publication 526 (Charitable Contributions) and Section 501(c)(3) Compliance.
- Legal Filings: All-Star Capital vs. Eddy Curry, New York State Supreme Court.
- NIL Legislation: Overview of state-by-state Name, Image, and Likeness statutes (2021-2024).
Article Contributed By:
Sid Peddinti, Esq. – Lawyer, Researcher, Publisher, AI Innovator
Keywords / Topics: NIL Financial Literacy, Athlete Family Offices, Philanthropic Tax Redirection, Asset Protection, Sports Foundations, Latrell Sprewell, Derrick Coleman, Eddy Curry.