Dear Friend,
Today, I want to talk about keeping what you make as a professional athlete. Professional athletes operate within a unique economic paradox: they earn a lifetime of income during a window that represents only a fraction of a traditional career.
While a corporate executive may have 35-40 years to build and preserve wealth, the average professional athlete has between 3.3 and 5.6 years to secure their financial future. This compression of earnings creates a high-stakes environment where wealth preservation is not just about growth, but about mitigating structural risks that can lead to rapid capital depletion.
Effective wealth preservation for high-earning athletes requires a multi-disciplinary approach that addresses tax complexity, career volatility, and the transition from active play to a “second act” in business or media.
Key Takeaways
- The 50% Rule: Successful athletes typically save at least 50% of their net earnings to sustain a multi-decade retirement.
- The “Jock Tax” Burden: Athletes often file tax returns in 15+ states annually due to nonresident income taxes in game-day jurisdictions.
- Specialized Protection: Standard disability insurance is insufficient; athletes require Permanent Total Disability (PTD) and Temporary Total Disability (TTD) riders.
- Jurisdictional Strategy: Establishing domicile in states like Florida, Texas, or Nevada can significantly reduce state-level tax liabilities on non-game income.
- Asset Shielding: Utilizing irrevocable trusts in favorable jurisdictions (e.g., WING, DING, NING) protects capital from creditors and legal disputes.
Table of Contents
- The Economic Reality of Professional Sports
- Structural Risks to Athlete Wealth
- The Professional Advisory “Quarterback” Model
- Strategic Tax Mitigation and Residency
- Risk Management: Specialized Insurance Products
- Asset Protection and Trust Jurisdictions
- Investment Philosophy: The 50% Rule
- Post-Career Transition and NIL Monetization
- Comparison: Traditional vs. Athlete Wealth Management
- Frequently Asked Questions (FAQ)
The Economic Reality of Professional Sports
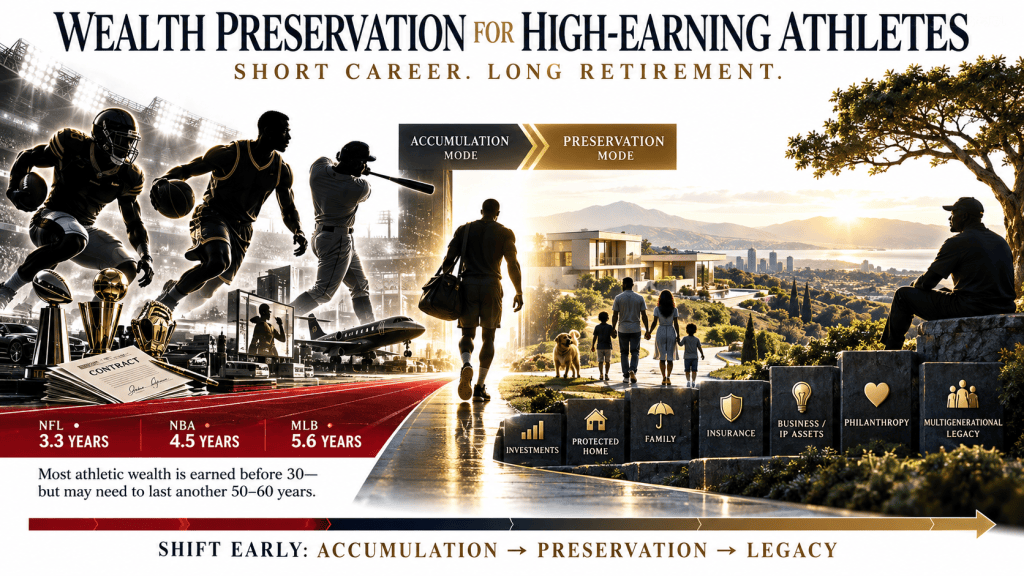
The primary challenge in athlete wealth management is the “short career, long retirement” cycle. According to data from various professional leagues, the average career length varies significantly by sport:
- NFL: ~3.3 years
- NBA: ~4.5 years
- MLB: ~5.6 years
Because the majority of an athlete’s liquid capital is generated before the age of 30, the money must be managed to last 50 to 60 years. This requires a shift from “accumulation mode” to “preservation mode” much earlier than the general population.
In my opinion, amateur and professional athletes need to become masters of legal, tax, and financial matters in order to ensure their wealth can be spread out for the next 40-60 years, and well beyond that, if they plan to leave a legacy behind. There is no other profession where you have this sudden explosion of income generated for your talents that suddenly and abruptly ends – with zero chance of you returning to that position again.
Once you retire from pro sports, you are not going to return as a pro athlete – maybe a coach, a trainer, educator, investor, or something else, but not a pro athlete. The need for anyone pursuing a career in sports needs to understand that first and foremost.
Structural Risks to Athlete Wealth
Lifestyle Inflation and Social Pressure
“Lifestyle creep” is the most common cause of financial distress among former athletes. Sudden wealth often brings a desire to match the spending habits of veteran teammates or to support an “entourage” of friends and extended family.
Without a strict budget, the high burn rate can outpace even the largest contracts, especially when considering that a $10 million contract may only net $5 million after taxes and agent fees.
The “Jock Tax” and Multi-State Compliance
Professional athletes are subject to the “Jock Tax,” a nonresident income tax levied by almost every state and many cities where they play. If an NBA player plays a game in California, they owe California taxes on the portion of their salary earned that day. This creates a massive administrative burden, often requiring the athlete to file 15 to 20 state tax returns per year. Failure to manage this “filing footprint” can lead to significant penalties and interest.
The Professional Advisory “Quarterback” Model
High-earning athletes should not manage their finances in a vacuum. A “quarterback” model involves a team of specialized professionals who provide checks and balances on each other:
- Fiduciary Financial Advisor: Must be a fiduciary, meaning they are legally obligated to act in the athlete’s best interest. They manage the investment portfolio and cash flow.
- Specialized CPA: Handles the complex multi-state tax filings and ensures the athlete is taking advantage of all available deductions.
- Legal Counsel: Reviews contracts, manages estate planning, and structures asset protection entities.
- Insurance Specialist: Procures high-limit disability and liability coverage tailored to professional sports.
Strategic Tax Mitigation and Residency
One of the most effective ways to preserve wealth is through legitimate domicile planning. By establishing a primary residence in a state with no personal income tax—such as Florida, Texas, Nevada, Washington, or Tennessee—athletes can shield their “off-field” income (endorsements, NIL deals, and investment gains) from state-level taxation.
However, residency must be “legitimate.” Tax authorities in high-tax states like New York or California often audit athletes to ensure they are actually spending the required amount of time in their claimed home state.
Risk Management: Specialized Insurance Products
Standard disability insurance does not cover the unique risks of a professional athlete. Specialized policies are required to protect the “human capital” of the player:
- Permanent Total Disability (PTD): Pays a lump sum if an injury or illness ends the athlete’s career permanently.
- Temporary Total Disability (TTD): Provides monthly benefits if an athlete is sidelined for a portion of a season, helping to cover living expenses while they are not receiving game checks.
- Loss of Draft Value: For collegiate athletes, this protects against a slide in draft position due to injury.
Asset Protection and Trust Jurisdictions
Athletes are high-profile targets for litigation, including frivolous lawsuits and complex divorce settlements. To safeguard assets, many advisors utilize Irrevocable Trusts.
Jurisdictions like South Dakota are frequently used because of their favorable laws regarding:
- Asset Protection: Stronger shields against creditors.
- Dynasty Provisions: Allowing wealth to pass through generations without repeated estate taxes.
- Privacy: Strict laws that keep the details of the trust out of the public record.
Investment Philosophy: The 50% Rule
The “50% Rule” is a benchmark where athletes aim to save at least 50% of their net (after-tax) income.
Investment strategies for athletes typically prioritize liquidity and stability over high-risk private equity or “get-rich-quick” schemes. While a tech entrepreneur might reinvest everything into a new venture, an athlete’s portfolio should focus on diversified equities, municipal bonds, and income-producing real estate to ensure a steady cash flow once the playing days end.
Post-Career Transition and NIL Monetization
The modern athlete has a significant advantage: Name, Image, and Likeness (NIL) rights. Wealth preservation now begins in college. By building a personal brand early, athletes can create “passive” income streams that continue long after they leave the field. This transition planning is essential to prevent the “identity crisis” and financial vacuum that often follows retirement.
Comparison: Traditional vs. Athlete Wealth Management
| Feature | Traditional Professional | High-Earning Athlete |
|---|---|---|
| Career Duration | 35–45 Years | 3–6 Years (Average) |
| Earnings Peak | Ages 45–60 | Ages 22–28 |
| Tax Complexity | Single State / Federal | 15+ States (Jock Tax) |
| Primary Risk | Market Volatility | Career-Ending Injury |
| Savings Target | 10%–20% of Gross | 50%+ of Net |
| Asset Protection | Standard Umbrella Policy | Irrevocable Trusts / PTD Insurance |
Frequently Asked Questions (FAQ)
What is the “Jock Tax”?
The Jock Tax is a nickname for the income tax levied by states and cities against nonresident professional athletes for work performed in that jurisdiction. It is calculated based on “duty days” or games played in that specific state.
Why do athletes need a fiduciary advisor?
A fiduciary is legally required to put the client’s interests first. This is critical for athletes who are often approached by “friends” or unvetted advisors pitching high-commission products or risky business ventures that do not align with long-term preservation.
How does a South Dakota Trust help an athlete?
South Dakota is a top-tier jurisdiction for asset protection. It allows for “Self-Settled Spendthrift Trusts,” which can protect an athlete’s assets from future creditors while still allowing the athlete to be a discretionary beneficiary.
What is the difference between PTD and TTD insurance?
PTD (Permanent Total Disability) is for career-ending injuries, providing a large lump sum. TTD (Temporary Total Disability) is for short-term injuries that keep an athlete out for weeks or months, providing a “paycheck” replacement during recovery.
Should athletes invest in private equity or startups?
While tempting, most advisors recommend that private equity make up only a small fraction (5-10%) of an athlete’s portfolio. The lack of liquidity in these investments can be dangerous if the athlete’s career ends unexpectedly.
Call To Action & Next Steps
Wealth preservation is a defensive game that requires an offensive strategy. If you are a high-earning professional or an advisor to one, the time to structure your “quarterback” team is before the first major contract is signed.
Comment below or take a second to send us a quick email if you’d like to attend a complimentary workshop or 1:1 call to discuss these strategies in more depth.
Article Contributed By:
Sid Peddinti, Esq. – Lawyer, Researcher, Publisher, AI Innovator
Keywords / Topics: Wealth Preservation for High-Earning Athletes, Jock Tax, Asset Protection, NIL Strategy, Athlete Financial Planning.
References & Sources
- [1] Forbes – Financial Planning for Professional Athletes: https://www.forbes.com
- [2] Conway Wealth – The Athlete’s Financial Playbook: https://www.conwaywealth.com
- [3] Scotiabank – Wealth Management for Professional Athletes: https://www.scotiabank.com
- [4] Postgame Financial – Career Longevity and Wealth: https://www.postgamefinancial.com
- [5] Courtside Wealth – Managing Sudden Wealth: https://www.courtsidewealth.com
- [8] Intuit TurboTax – Understanding the Jock Tax: https://www.intuit.com
- [9] BPM LLP – Tax Strategies for Athletes: https://www.bpm.com
- [11] Baker Tilly – Multi-state Tax Compliance for Athletes: https://www.bakertilly.com
- [14] Sutton Special Risk – PTD and TTD Insurance Explained: https://www.suttonspecialrisk.com
- [16] Moment Private Wealth – The 50% Rule for Athletes: https://www.momentprivatewealth.com
- [18] Morgan Stanley – Global Sports & Entertainment Division: https://www.morganstanley.com